Why the Months After Heads of Terms Now Decide What You Keep
Introduction
Helen had done the hard part, or so she thought. Her facilities services business in the South West turned over £6m, made a little under £900k in normalised earnings (profit adjusted for one-off and owner-specific costs, so a buyer sees the true run-rate), and had attracted a trade buyer she liked. Heads of terms were signed in March. Heads of terms are the non-binding summary of the main deal points. Her corporate finance adviser expected completion by early summer.
It completed in November, at a lower price.
Nothing dramatic went wrong. The buyer's accountants asked for three years of management accounts reconciled to the statutory accounts, and it took five weeks to produce them. Their lawyers asked for signed copies of the top ten customer contracts. Two of them had never been signed, and one had rolled on month to month since 2022. They asked which employees held written contracts, and the answer was fewer than Helen had assumed. Each request was reasonable. Each answer took time. Each gap gave the buyer a reason to revisit the price.
Helen is a composite, drawn from patterns common in owner-managed sales rather than from any single business. Her experience is becoming more typical, and the rest of this article is about preparing for it.
1) Why Diligence Is Taking Longer
Due diligence is the buyer's detailed investigation of your business before they commit, covering the finances, contracts, people and legal position. It has always been thorough. What has changed is how long it takes and how hard buyers press.
Experian's review of UK deals in the first quarter of 2026 found that more extensive due diligence has lengthened the gap between a deal being announced and completing. It also found that buyers are completing fewer deals than a year earlier, though larger ones, which points to buyers who can afford to be selective.
Looking back at 2025, Crowe's 2026 mid-market outlook found that deals stalled or fell away where the quality of earnings was poorly explained, the financial information was under-prepared, or the owner's price expectations were out of line with the market.
For an owner, this means the hardest scrutiny now falls after you have agreed terms. By then you have usually granted exclusivity - a period in which you agree not to talk to other buyers - so you have less room to move.
Founder Insight: "The relief that comes too early". Signing heads of terms feels like the finish line. It's natural to relax, tell a few people, and start thinking about what comes next. The buyer's team is just starting. Treat the signature as the start of the most demanding stretch of the sale.
2) What the Buyer's Team Actually Tests
Every buyer has its own checklist. In an owner-managed business, the questions tend to fall into five areas.
- Earnings quality. Do the profits you are selling on hold up once the buyer's accountants have adjusted them? They will test every add-back (a cost you say won't continue after the sale) and ask for evidence behind each one.
- The forecast. If the price reflects growth, the buyer will test the forecast against your pipeline, your pricing history and what your current year is actually delivering.
- Contracts. Are your key customer and supplier agreements signed, current, and free of change-of-control clauses? A change-of-control clause lets the other party end the contract if the business changes hands.
- People. Who holds written contracts, who is critical to delivery, and what happens to the business if those people leave.
- Compliance and tax. Whether licences, filings, employment obligations and tax positions are in order, and whether anything could come back on the new owner after completion.
None of this is new. What has changed is that buyers now check each area in more depth and are slower to accept an owner's word where they could see a document.
Action step: Take the five areas above and, for each, write down the one question you would least like a buyer to ask. That list is where your preparation starts.
3) How a Long Diligence Costs You
Delay costs you more than time. Three things happen while diligence drags on.
First, the buyer gets more chances to revisit the price. Each gap they find becomes a reason to ask for a reduction, which advisers call a price chip. Each chip may be small, but after two or three the gap between the headline price and what you receive becomes significant.
Second, the business has to keep performing. The buyer is watching your monthly numbers throughout. A soft month in the middle of a long diligence gives them another reason to renegotiate, even when it says little about the business over a full year.
Third, you get tired. Diligence runs alongside the day job, and without a finance team the document requests fall to you. After months of it, owners can find themselves accepting terms they would have refused at the start, because agreeing is the fastest way to end the process.
🚩 Diligence Flag: "The month that moves the price". Where a buyer has agreed a price against the last full-year accounts, current trading is still watched closely. If a seasonal dip or a lost contract lands during diligence, expect it to be raised. The pre-emptive move is to share a realistic current-year forecast, with its seasonality explained, before heads of terms. A dip the buyer was told about in advance is much harder to use as a reason to cut the price.
4) Building the Pack Before You Need It
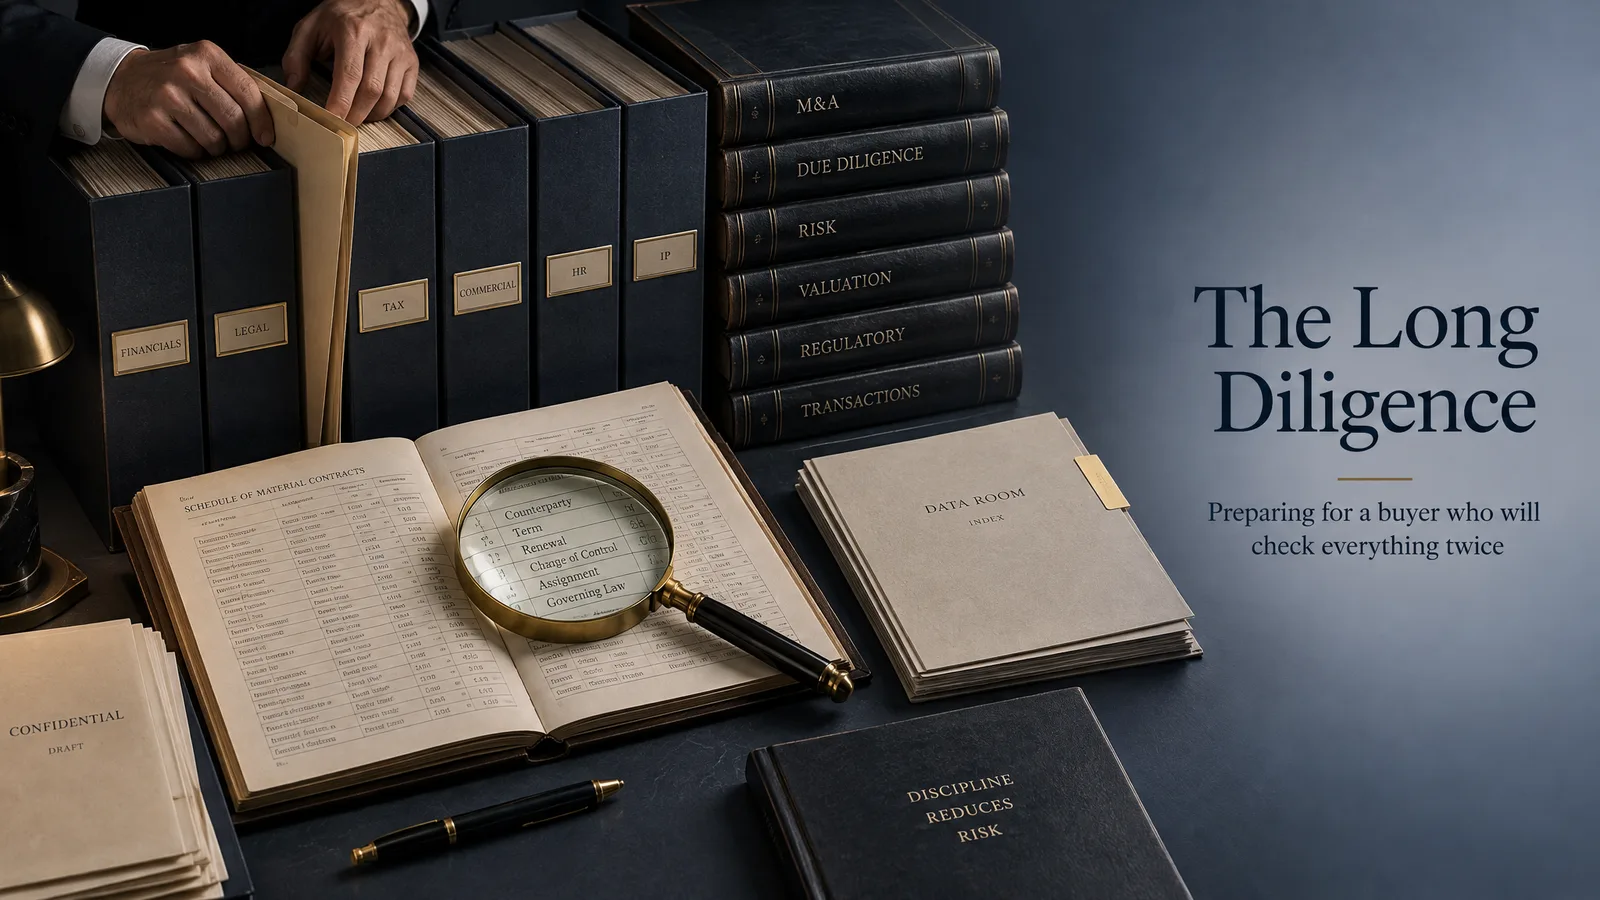
Aim to have most of what a buyer will ask for assembled before any buyer is involved. Advisers call the organised set of documents a data room. It is usually a secure online folder, but the documents in it matter more than the software.
Build it in the order a buyer will ask for it:
- Financial. Three years of statutory accounts reconciled to management accounts, a clear schedule of add-backs with the evidence behind each one, aged debtors, and a current-year forecast you can defend line by line.
- Commercial. Signed contracts for your main customers and suppliers, a note of any change-of-control clauses, and figures for revenue concentration and customer retention.
- Legal and corporate. Share register, articles, shareholder agreements, property leases, intellectual property ownership, and any disputes past or present.
- People. Employment contracts, an organisation chart, key-person arrangements, and any outstanding employment issues.
- Operational. Licences, certifications, insurance and health and safety records, plus how the business runs day to day when you are not there.
The purpose is to find out what is missing while you still have time to fix it. Helen could have had both unsigned contracts signed in an afternoon had she known about them a year earlier.
Action step: Run the first two categories yourself this quarter. Where you cannot produce a document within a day, mark it. Those marks become your preparation plan.
5) Clear What You Can, Contain What You Can't
Once you have seen the gaps, sort them.
Most can simply be fixed: sign the contract, formalise the employment terms, reconcile the accounts, renew the licence. Do this before you go to market.
Some cannot be fixed in time. A dispute may still be running, a large customer may be up for renewal after the likely completion date, or a key manager may have no successor yet. For each of these, decide how you will present it and how the deal structure could handle it. That might mean a specific indemnity, an adjustment to the payment terms, or a disclosure made early and in full.
In our experience, what you present up front and explain calmly costs you far less than what the buyer finds for themselves. A problem disclosed early is judged on its merits. One discovered by the buyer makes them doubt everything else you have told them.
🚩 Diligence Flag: "The contract nobody signed". An unsigned or long-expired customer contract gives a buyer's lawyers an easy finding. It can lead to a request to hold back part of the price until the contract is signed or renewed. The pre-emptive move is a contract audit twelve months before a sale: get the key agreements signed and check each one for change-of-control terms.
Action step: For every gap you can't close, write one plain paragraph: what it is, why it exists, and what you are doing about it. If you can't write that paragraph clearly, a buyer's adviser will write their own version of it.
Preparing for a Buyer Who Checks Everything
The market is open for well-prepared businesses. Buyers are active, and the ones completing deals have money to spend. They are also slower and more thorough than they were, and the extra time they take tends to work in the buyer's favour.
The most practical thing you can do is prepare for diligence before it starts. Assemble the documents, find the gaps, fix what can be fixed, and decide how you will present what can't. That work is ideally done 12-24 months before a sale, and it is useful even with less time than that.
If you'd like a clear view of what a buyer's team would find in your business, and what to do about it first, we'd be glad to talk it through.
About Exit Strategy & Solutions
Exit Strategy & Solutions is a specialist advisory firm helping UK SME owners build optionality, maximise value, and reduce risk through strategic exit planning and execution.
Our approach combines deep market intelligence, strategic positioning expertise, and an unwavering focus on protecting your interests at every stage.
Ready to explore your exit options?
Take our Exit Readiness Calculator to assess your business's exit readiness and identify opportunities to maximise valuation here: https://exitstrategyandsolutions.com/resources/calculator
Contact us:
- Email: enquiry@exitstrategyandsolutions.com
- Phone: 0330 043 4689
- Website: www.exitstrategyandsolutions.com
Disclaimer
This article is provided for informational purposes only and does not constitute legal, tax, or regulated investment advice. Examples cited are based on composite scenarios for illustrative purposes. Exit Strategy & Solutions is not responsible for decisions made based on information in this article.