Deciding on Purpose, Before the Market Decides for You
Introduction
Lorna is a fictional composite, drawn from situations common to owner-managed businesses. She is not a client.
Lorna had run her building services business in Somerset for twenty-two years when a larger group rang to ask whether she had ever thought about selling. She said she would think about it. That evening she realised she had no idea what she thought.
It's a common place to be. Most owners spend years answering "how is the business doing?" and almost no time on "do I want to keep doing this?" When a buyer calls, the second question arrives without warning, and the buyer's timetable starts running before you have an answer.
A call like that is flattering, and it's easy to drift from there. You agree to a coffee, then to sharing a few numbers, then to a second meeting, and each step feels small. A few weeks later you're answering a buyer's questions about a sale you never actually decided to make.
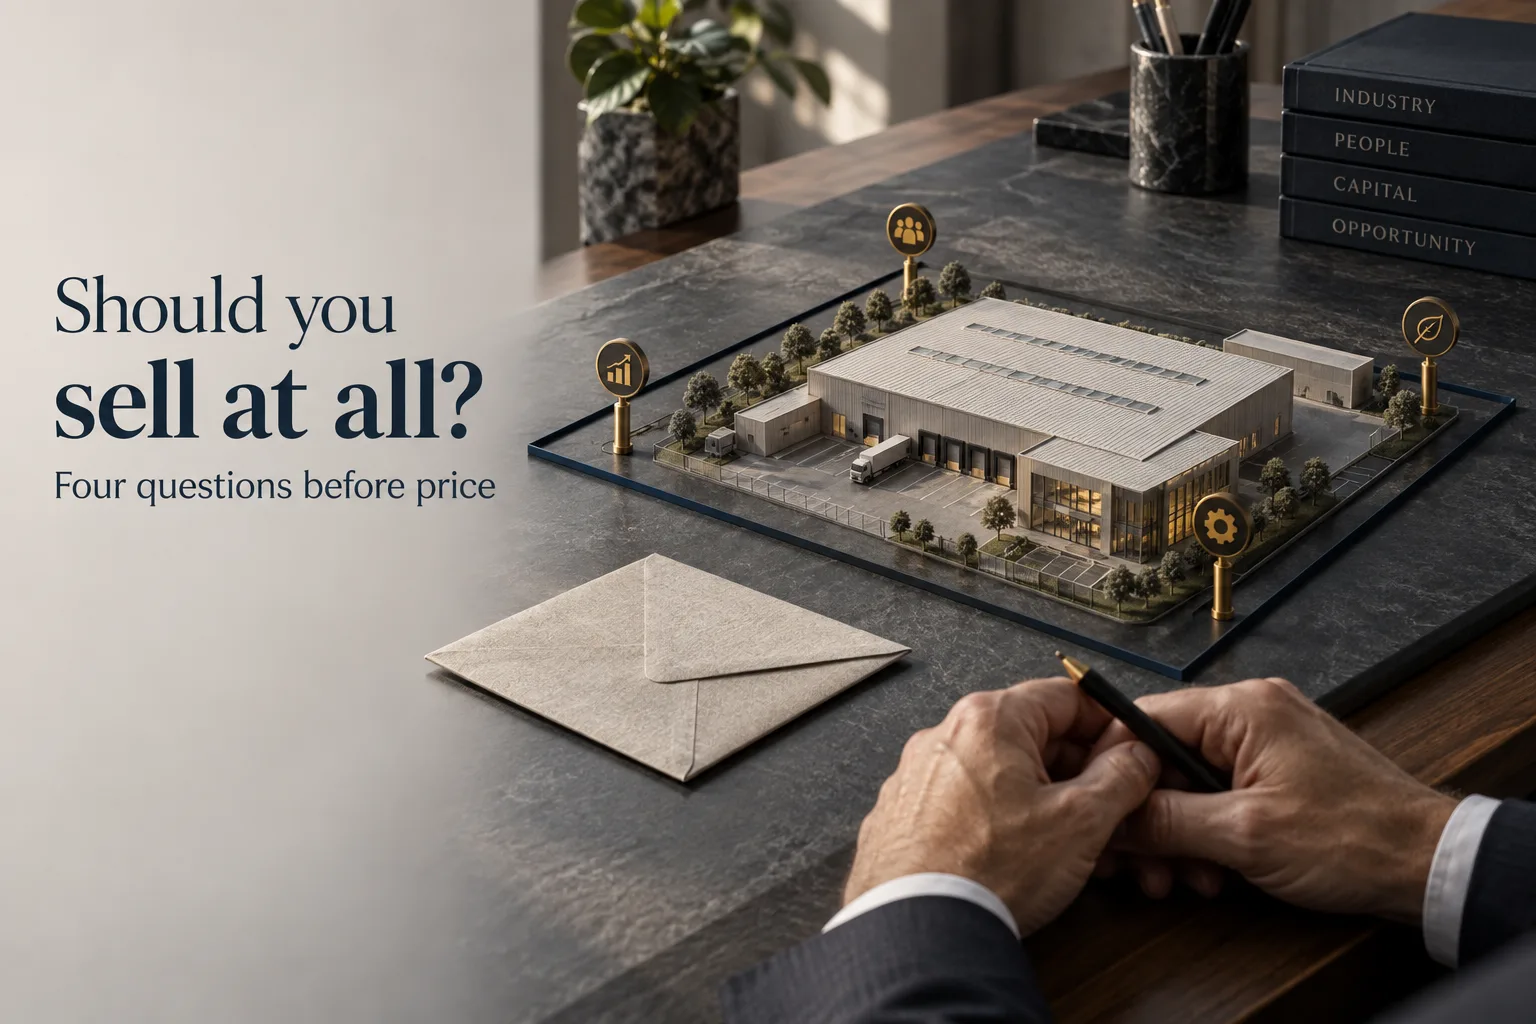
Before you think about value, buyers or tax, settle four questions. They decide whether selling is right for you at all, and you want your answers before anyone else asks.
1) What Do You Want the Next Ten Years to Look Like?
Lorna's first instinct was to talk about the price. Her second, a week later, was to talk about her daughter's wedding, the walking holiday she had put off three times, and her worry about what would happen to the twelve people who had worked for her for more than a decade.
Start with what you want the sale to give you: more time, financial security, a new venture, or simply less responsibility. Owners who start there make better decisions about everything that follows, including whether a sale is the way to get it. For some, the answer turns out to be a good manager and a four-day week.
Be specific. "Retire" means something different to every owner who says it. If you want more time, how many days a week do you still want to work? If you want security, what income do you need, and from when? Answers at that level turn a feeling into something you can test a sale against.
Then ask the people closest to you the same question. Lorna's husband assumed she wanted to stop working altogether. She didn't. She wanted to stop being the person every problem came back to, and a sale was only one way to get there.
Action step: Write one page describing an ordinary week three years from now: where you are, what you spend your time on, and what income pays for it. Keep it where you'll see it when a buyer calls.
2) Could the Business Run Without You?
When Lorna wrote down the decisions she took in a normal month, almost all of them were hers alone. Customers rang her mobile. Her operations lead was excellent on site and had never priced a job.
This matters for two reasons. First, a buyer will pay less, or pay later, for a business that depends on its owner, because they have to run it without you once the sale completes. Second, if you can't step away, you can't choose freely between selling and keeping the business: it makes the choice for you. I'd recommend reducing the business's dependence on you whether you sell or not, because it keeps both options open.
I've been through this myself. In the early years of the business I built in Hong Kong, I received more than one offer to buy it, and I turned them down. I quickly understood the value of preparing.
Over the next two to three years I did almost everything I now recommend to owners. I delegated, hired senior managers, divided responsibilities clearly and documented how the business ran. A large part of the business's dependence on me went with it.
The next offer, from a listed company, came at a much higher value than any before it. That's why this is the question I take most seriously with any owner.
Dependence on the owner usually shows in three places: customers who deal only with you, decisions only you take, and knowledge that lives only in your head. Pick the one a buyer would find most concerning and start there.
For Lorna, it was pricing. Her operations lead began pricing jobs alongside her, then on his own with Lorna checking his figures, then on his own. Within a year, half the quotes leaving the business had never crossed her desk.
Founder Insight: "Handing over the customers." In my experience, handing over customer relationships is the hardest step, because it feels like giving away the thing that made the business work. Do it gradually. Bring your successor into calls you'd normally take alone, then let them lead while you stay in the background, until customers stop asking for you.
3) What Is It Really Worth, and What Would You Need?
Lorna had a number in mind. It had come from a conversation at a dinner three years before, about a business in a different trade.
Most owners carry a figure like this, and few have tested it. Put two numbers side by side: what the evidence suggests a buyer would pay, and what you need from a sale to live the next ten years the way you want. If the first is well below the second, you want to know that before a buyer tells you. It changes your question from "should I sell?" to "what would have to change first?"
The first number starts with your accounts, adjusted for anything a new owner wouldn't carry on paying, such as your own salary where it is well above or below what a manager would cost. That adjusted profit is then set against what businesses like yours have actually sold for. The second number starts with your own finances: what you need after tax and fees to live the week you described in the first question.
Look past the headline figure too. A buyer may pay part of the price later, or only if the business hits agreed targets after the sale. What matters to you is how much reaches your bank account, and when.
Lorna's two numbers were further apart than she had expected, and that told her what the next eighteen months needed to achieve.
Action step: Ask your accountant for your last three years' accounts with your own pay and any one-off costs shown separately, so you can see the profit a buyer would see.
4) Who Else Has a Say?
Lorna owned 70% of the business. Her former business partner, long retired, owned the rest, and had views.
Other shareholders, a spouse, children in or out of the business, key staff who were promised something years ago: any of them can slow or stop a sale if they hear about it last. Talk to them before any buyer is involved.
Some of these people have rights on paper, such as a shareholder whose agreement the sale needs. Others have none on paper and a great deal of influence in practice. Read your shareholders' agreement and your articles of association (the company's formal rules) before anyone else does. A buyer's lawyers will read them closely, and you want to know first what they say about selling shares.
Lorna's former partner had always assumed his shares were worth a figure he'd once heard from a friend. Agreeing a fair value with him took months, and it was far easier with no buyer waiting.
If a Buyer Has Already Called
My first piece of advice is to take your time before responding. A buyer who is seriously interested will still be interested in a few weeks, and a short, polite reply costs you nothing: thank them, say you're open to a conversation in due course, and leave it there.
Before you share anything about the business, ask them to sign a confidentiality agreement, which commits them to keeping what you tell them private. Keep the first information you share to the general picture. Detailed accounts, customer names and staff costs can wait until you know who you're dealing with and why.
Ask them what they want the business for. Would they keep the name, the premises and the team? Who would run it after you? A buyer who talks about a grand vision but can't answer those questions plainly hasn't yet got a plan for your business.
Don't agree at this stage to talk to them alone. Once you agree to deal with one buyer only, you lose most of your bargaining power, so I'd hold off until you know whether you want to sell and have seen what else might be available.
Then work through the four questions above. The call may turn out to be the start of a good sale. You'll make a far better decision about it once your own answers come first.
What Lorna Decided
In the end Lorna told the group she wasn't ready to sell. She spent the next eighteen months handing customer relationships to her operations lead, agreeing a value for her former partner's shares, and moving to monthly accounts. When she did talk to buyers, she talked to three, on her own timetable, and could compare their offers side by side.
My advice to any owner is the same: decide on purpose, before the market decides for you. Buyers are checking more thoroughly than they used to, and UK deals are taking longer to complete. If you're still working out what you want when a buyer calls, you're at a disadvantage from the first conversation.
If You're Facing This Decision
You don't need the answer before you talk to someone. I'd recommend talking it through with someone who is on your side and has nothing riding on what you decide.
That's what The Sale Decision is for. We work through it with you: whether to sell, keep the business, respond to an approach, or appoint a corporate finance firm to run a sale. You come away with a written record of where each route leads, including the routes that lead away from a sale. Our fee for this advice never depends on a sale happening.
About Exit Strategy & Solutions
Exit Strategy & Solutions is a specialist advisory firm helping UK SME owners build optionality, maximise value, and reduce risk through strategic exit planning and execution.
Our approach combines deep market intelligence, strategic positioning expertise, and an unwavering focus on protecting your interests at every stage.
Ready to explore your exit options?
Take our Exit Readiness Calculator to assess your business's exit readiness and identify opportunities to maximise valuation here: https://exitstrategyandsolutions.com/resources/calculator
Contact us:
- Email: enquiry@exitstrategyandsolutions.com
- Phone: 0330 043 4689
- Website: www.exitstrategyandsolutions.com
Disclaimer
Exit Strategy & Solutions Ltd is not authorised or regulated by the Financial Conduct Authority. We do not give legal, tax, insurance or regulated financial advice.
This is general information, not advice on your own circumstances.
Exit Strategy & Solutions Ltd is not authorised or regulated by the Financial Conduct Authority. We do not give legal, tax, insurance or regulated financial advice.
This is general information, not advice on your own circumstances.